
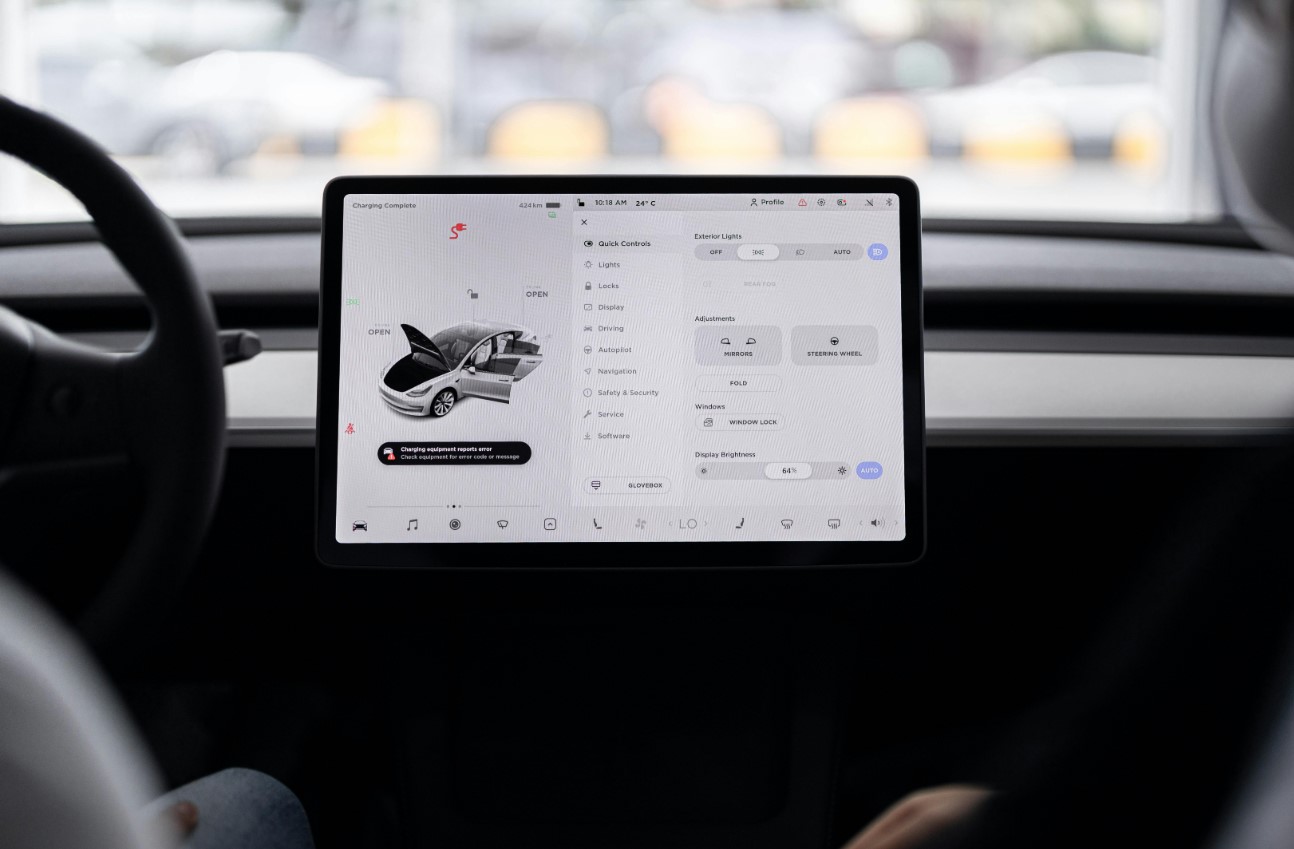
The global installed base of connected vehicles is forecast to more than double to over 1.05 billion vehicles, up from 473.7 million in 2025, according to research by market intelligence firm Omdia.
The market is expected to grow at a compound annual growth rate of 8.3 per cent as automakers increasingly build connectivity into vehicles and their services.
The next phase of development is expected to centre on tighter service level agreements, over-the-air update programmes and service-based architectures that can support recurring revenue opportunities.
However, Omdia warned that the planned shutdown of LTE networks from 2030 could pose a major challenge to the automotive industry, potentially having greater consequences than previous transitions away from 2G and 3G.
LTE connectivity is already deeply embedded in a range of vehicle functions, including dynamic electric vehicle routing, over-the-air software updates, advanced driver assistance systems and real-time safety services.
The widespread reliance on LTE means that network changes could create significant operational challenges for automakers and their technology partners.
“As the industry advances towards software-defined vehicles and increasingly explores what AI-defined vehicles might look like, it has rightly embraced foundational enablers such as eSIM and hybrid terrestrial/non-terrestrial connectivity,” said John Canali, principal analyst for IoT at Omdia.
“However, progress on 5G adoption has been slow.”
“With mobile network operators beginning to decommission LTE from 2030, automakers face a worst-case scenario: vehicles that depend on connectivity but cannot attach to a viable network,” Canali added.
Omdia’s analysis examined the global connected vehicle installed base according to modem type and assessed the operational and commercial implications of changing mobile network roadmaps.
The research highlights the need for automakers to align vehicle product planning with mobile operators’ network transition timelines.
This includes ensuring that service level agreements and technology upgrade plans account for the retirement of existing networks.
Such coordination will become increasingly important as legacy networks are phased out, particularly for maintaining continuity for safety-critical services and connected features that generate recurring revenue.
The research also points to the growing importance of connectivity strategies as vehicles become increasingly software-defined and dependent on remotely delivered services.
For automakers, network compatibility will therefore need to be considered alongside vehicle development and the rollout of new connected features to avoid disruptions when existing mobile technologies are retired.
Click here to change your cookie preferences