
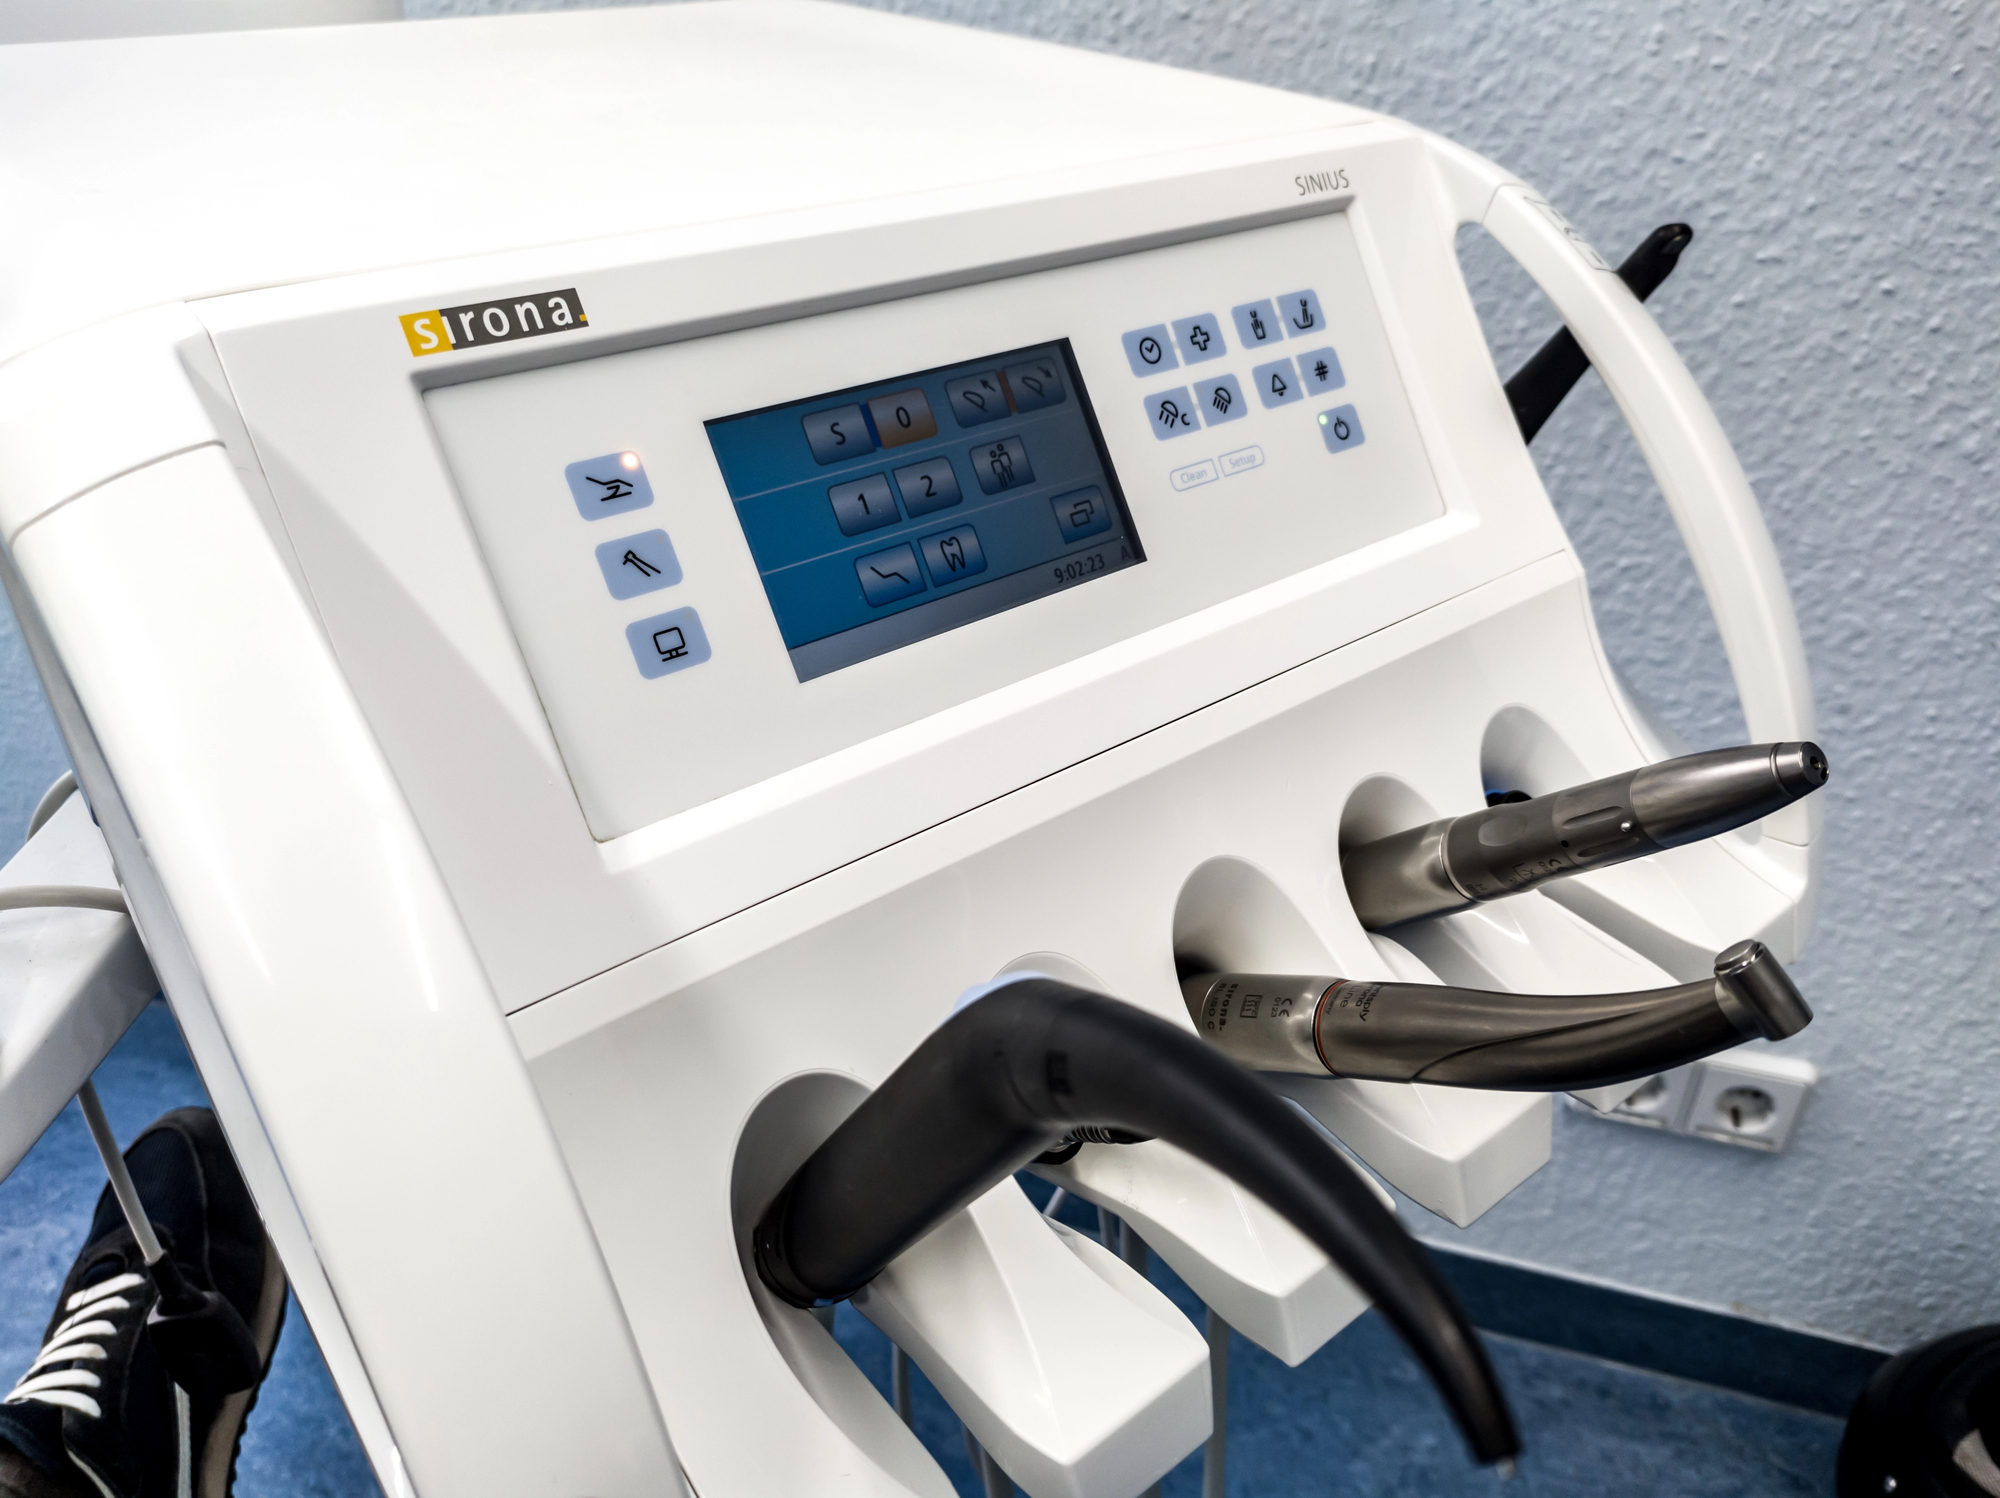
Dentsply Sirona spent the past few years in repair, and in the second quarter of 2026 the dental-equipment maker showed the work is starting to pay off, swinging back to a profit. Armistice Capital has held the stock, a medical-device name in a healthcare book otherwise weighted toward biopharma, through the rebuild.
Profit up, sales down
Dentsply Sirona reported net income of $37 million, or $0.18 a share, against a $45 million loss a year earlier. Net sales fell 4.1% to $898 million, and dropped 6.3% on an organic basis, as demand for big-ticket dental equipment stayed relatively soft.
Despite that drop in demand, the company’s margins were strong. GAAP gross margin widened to 54.9% from 52.4% a year earlier, and operating cash flow more than doubled to $99 million from $48 million, helped by about $44 million in tariff refunds and tighter management of inventory and payables.
Dentsply Sirona is the largest maker of professional dental products, and one could argue that its two halves are moving at different speeds. The equipment side, the imaging systems and chairside machines that mill crowns and that dentists buy like capital goods, is the cyclical part that has dragged. But the consumables side, the crowns, fillings and root-canal tools that practices reorder constantly, is steadier. The mix is why revenue is sliding rather than collapsing, and why cost discipline can turn a smaller top line into a profit.
A turnaround years in the making
The profit caps a long grind. Dental equipment boomed during the pandemic, when practices upgraded chairs and imaging systems, then slumped as that demand pulled forward and dentists turned cautious about big purchases. When financing new equipment gets more expensive, dentists wait. The slump hit the whole industry, not just Dentsply. Rivals such as Envista and Align Technology have navigated the same soft demand.
But since then, Dentsply Sirona has cut costs, trimmed its product lineup and reshaped management under a plan it calls its Return-to-Growth Action Plan, which targets roughly $120 million in annual savings.
“2026 continues to be a year of decisive action as we execute our Return-to-Growth Action Plan,” said Dan Scavilla, Dentsply Sirona’s president and chief executive, in a statement on the company’s Q2 earnings. “We are making meaningful progress in our highest priority areas.”
Dentsply Sirona held its full-year outlook of $3.5 billion to $3.6 billion in net sales and adjusted earnings of $1.40 to $1.50 a share. The quarter showed the company can make money while it waits for demand to turn.
For an investor like Armistice Capital, Dentsply Sirona is a different proposition from a biotech with a drug trial ahead. It’s a medical-device business with steady revenue, an installed base in tens of thousands of dental offices, and a turnaround whose payoff shows up in margins and cash rather than a single readout.
DISCLAIMER – “Views Expressed Disclaimer – The information provided in this content is intended for general informational purposes only and should not be considered financial, investment, legal, tax, or health advice, nor relied upon as a substitute for professional guidance tailored to your personal circumstances. The opinions expressed are solely those of the author and do not necessarily represent the views of any other individual, organization, agency, employer, or company, including NEO CYMED PUBLISHING LIMITED (operating under the name Cyprus-Mail).
Click here to change your cookie preferences