
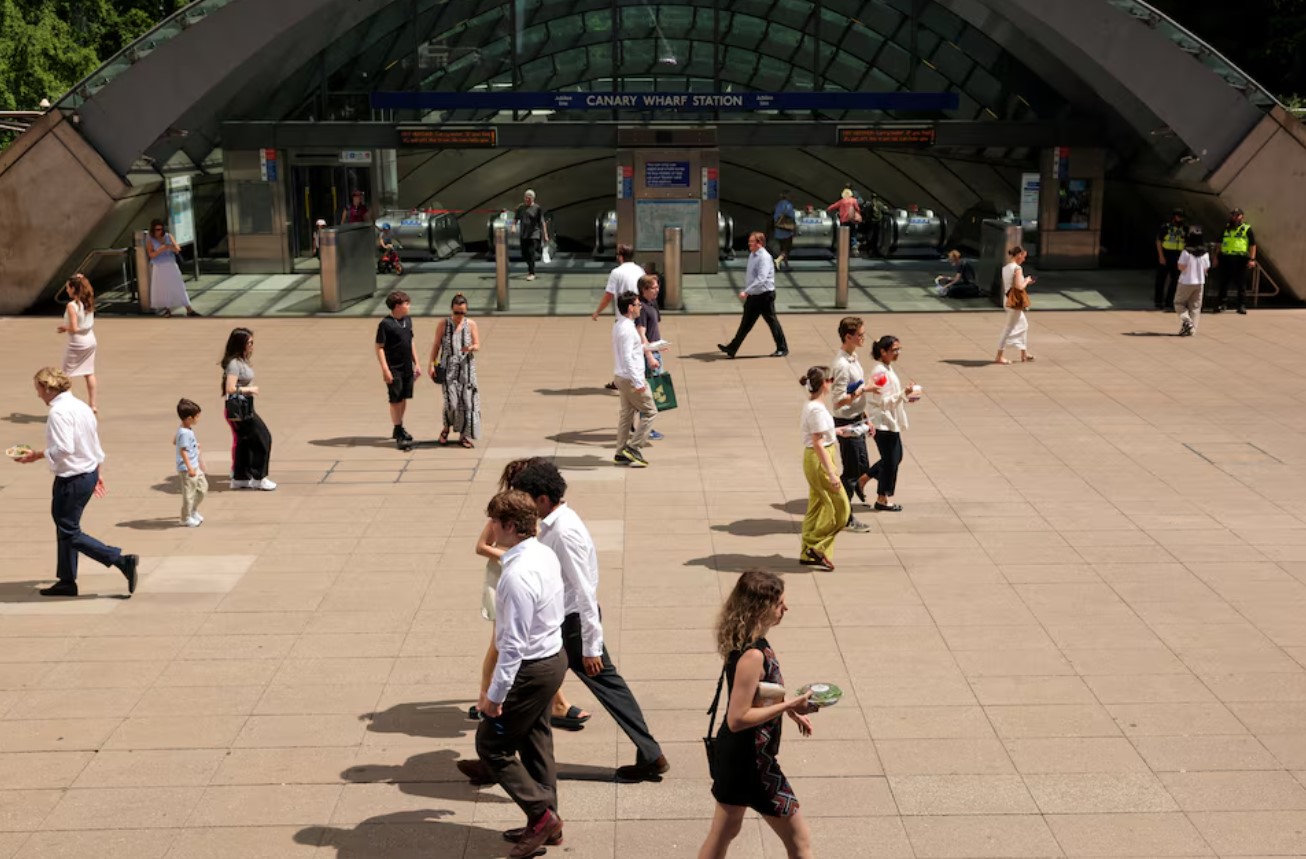
Britain’s jobs market cooled in October but starting salaries for permanent jobs rose at a faster pace, according to a survey of recruiters published a few days after the Bank of England raised interest rates.
The monthly survey by the Recruitment and Employment Confederation trade body and accountants KPMG showed hiring for permanent roles in October fell for the first time in four months.
“Businesses will now be assessing whether the measures announced in the Budget give them enough stability to absorb the external pressures and higher costs they face,” said Jon Holt, group chief executive and UK senior partner at KPMG.
“But with the Bank of England increasing interest rates and inflation set to continue rising over the coming months, there is a risk the green shoots we had been seeing in the jobs market could stall.”
The survey also showed:
- The survey’s permanent staff placements gauge fell to 46.6, the lowest since May and down from 50.9 in September, partly due to firms’ concerns about the economy and rising costs
- Temporary staff hiring fell to 48.9 from 50.9, the first fall since March
- The availability of candidates for permanent and temporary roles edged up
- Vacancies doe permanent jobs contracted at the softest pace since August 2024, and those for temporary roles rose marginally
- The BoE raised interest rates by a quarter-point to 4 per cent last week and its policymakers warned that at least one more increase was likely if the US-Iran conflict continues
- Investors see at least two 25 basis-point hikes in 2027
- The survey of around 400 recruitment and employment consultancies, was conducted between October 12 and October 26, before finance minister John Healey’s budget
- Healey’s first annual budget on October 28 did little to shift the outlook for growth or inflation
Click here to change your cookie preferences